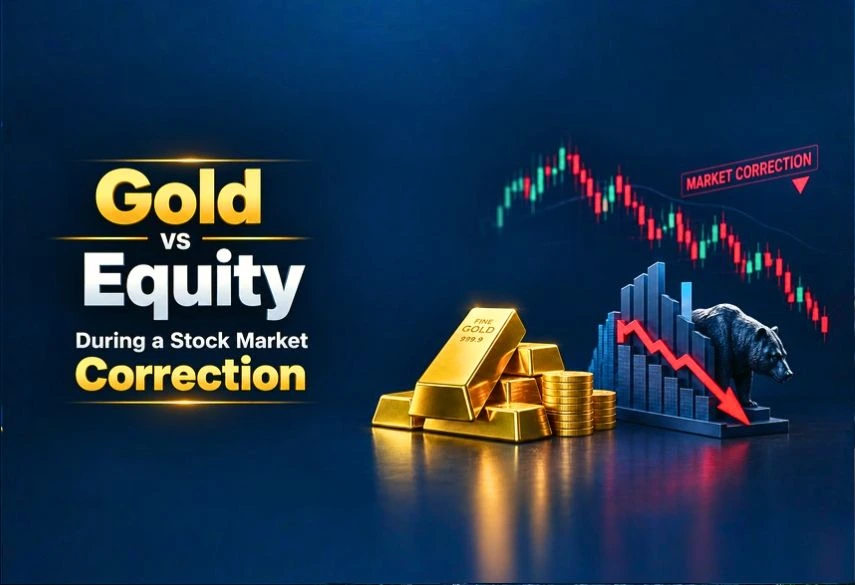
When stock markets fall sharply, investors often ask the same question: Should I move money from equities to gold? The short answer is that gold and equities play very different roles.
Gold has historically provided useful diversification during several periods of severe market stress, while equities are primarily growth assets whose returns depend on business earnings and economic expansion. For most long-term investors, therefore, the more useful question is not gold vs. equity, but how much of each asset fits into a diversified portfolio.
This distinction matters most during a stock market correction, when short-term fear can lead to poor investment decisions.
Gold vs Equity: The Key Difference
Equity represents ownership in businesses. If companies grow their profits over time, shareholders can benefit through rising share prices and dividends.
Gold does not generate business profits, cash flows, or dividends. Its investment role is different. Investors often use it as a store of value and as a diversifier because its price does not always move in the same direction as equities.
|
Factor |
Equity |
Gold |
|
Primary role |
Long-term capital growth |
Diversification and store of value |
|
Income generation |
Can generate dividends |
No regular income from gold itself |
|
Volatility |
Can be high |
Can also be volatile |
|
Crisis behaviour |
Can experience sharp drawdowns |
Often more resilient during systemic stress |
|
Main return drivers |
Earnings, economic growth, valuations |
Interest rates, currency, demand, inflation expectations |
|
Portfolio role |
Growth asset |
Diversifying asset |
Neither asset is automatically “better.” Their usefulness depends on the investor's time horizon, risk tolerance and overall asset allocation.
What Is a Stock Market Correction?
A market correction generally refers to a decline of around 10% or more from a recent market high. A decline of 20% or more is commonly described as a bear market, although definitions can vary.
Corrections can happen because of:
-
Economic slowdowns
-
Changes in interest rates
-
Geopolitical events
-
Financial crises
-
Unexpected events such as pandemics
-
Excessive market valuations
-
Sudden changes in investor expectations.
For an equity investor, these periods can be uncomfortable because portfolio values may fall quickly even when the investor's long-term financial goals have not changed. That is where diversification becomes important.
What Happens to Gold When Stocks Fall?
Gold is often described as a safe-haven asset, but that does not mean gold rises every time stocks fall. Its behaviour depends on the reason behind the market decline, movements in interest rates, the US dollar, liquidity conditions and investor demand.
However, during several periods of severe systemic stress, gold has historically shown greater resilience than equities.
A 2026 World Gold Council analysis of Indian portfolios found that gold had generally displayed a negative correlation with equities across many periods and had helped limit portfolio drawdowns during several systemic-risk events. Its calculations used Indian equity, bond and gold data in INR.
That diversification benefit is the main reason investors consider gold as a hedge during a stock market correction.
Gold vs Equity During the 2008 Financial Crisis
The 2008 Global Financial Crisis provides one of the clearest examples of why asset diversification matters. Indian equities suffered an exceptionally severe decline during the crisis.
NSE research shows that the Nifty 50 Total Return Index experienced a calendar-year maximum drawdown of roughly 45% in 2008. A maximum drawdown measures the fall from a peak to the subsequent trough rather than simply comparing January and December values.
Gold behaved differently during the broader financial crisis.
World Gold Council analysis of systemic-risk periods shows that INR-denominated gold was considerably more resilient than Indian equities during the Great Recession period.
The important lesson is not that gold will always rise during a crash. It is that assets with different return drivers can reduce the damage caused when one part of a portfolio falls sharply.
Gold vs Equity During the COVID-19 Crash
The COVID-19 shock in early 2020 caused one of the fastest major equity-market declines in modern history. Gold also experienced periods of volatility when investors initially rushed for liquidity. However, its performance over the full year was very different from the brief panic phase.
According to the World Gold Council, gold returned approximately 27.6% in Indian rupee terms during 2020, based on the LBMA Gold Price PM converted into INR. World Gold Council data also showed Indian domestic gold prices ending 2020 around 28% higher than the previous year.
This illustrates an important point:
The performance of gold during a few days of market panic can be very different from its performance across an entire crisis period.
Investors should therefore be careful when comparing a stock-market peak-to-trough drawdown with gold's calendar-year return. The dates and measurement method must be the same for a fair comparison.
Why Gold Can Help Indian Investors During Global Stress
Gold prices in India are influenced not only by the international price of gold but also by movements in the Indian rupee. International gold is largely quoted in US dollars.
As a simplified example, if:
-
International gold prices rise, and
-
The rupee weakens against the dollar.
The increase in domestic gold prices can be greater than the increase in dollar-denominated gold. The reverse can also happen. Currency movements are therefore one reason why gold's returns for an Indian investor may differ from returns quoted in international financial news.
Does Gold Always Rise When Equity Falls?
No. This is one of the most important limitations investors should understand. Gold can also fall during an equity correction.
For example, investors may temporarily sell gold during a liquidity crisis because they need cash. Gold prices can also face pressure when real interest rates rise or when market conditions reduce investor demand for non-yielding assets.
Gold has experienced prolonged weak periods in the past as well. Therefore, gold should be treated as a diversifier, not as a guaranteed crash-protection product. That distinction matters because investors who buy gold only after a major price rally may still experience losses.
Gold vs Equity Returns Over the Long Term
Comparing gold and equities only during crashes gives an incomplete picture. Equities and gold generate returns for fundamentally different reasons. Why equities can create long-term wealth. Companies can:
-
Increase revenue
-
Improve profitability
-
Launch new products
-
Expand into new markets
-
Reinvest profits
-
Distribute dividends.
As businesses and the economy grow, long-term shareholders can participate in that growth.
Why gold behaves differently
Gold does not generate earnings. Its value is influenced by factors such as:
-
Inflation expectations
-
Interest rates
-
Currency movements
-
Central-bank demand
-
Jewellery and investment demand
-
Geopolitical uncertainty
-
Investor risk appetite.
This means there can be long periods when equities outperform gold and other periods when gold performs significantly better.
Comparing the two solely on the basis of one crisis can therefore lead to misleading conclusions.
Correlation Matters More Than Picking a Winner
The main investment case for combining equity and gold comes from correlation. Correlation measures how closely two assets move together. If two investments always rise and fall together, combining them provides limited diversification.
If their return patterns differ, combining them may reduce overall portfolio volatility.
World Gold Council research published in 2026 found that adding gold to a hypothetical INR portfolio improved risk-adjusted returns and reduced drawdowns over the 19 years analysed. In that specific study, gold allocations ranging from 7.5% to 15% produced stronger risk-adjusted results than the portfolio without gold.
This should not be interpreted as a universal recommendation that every investor should hold exactly 7.5%–15% in gold. The appropriate allocation depends on factors such as:
-
Investment horizon
-
Age and financial goals
-
Emergency-fund requirements
-
Existing asset allocation
-
Income stability
-
Risk tolerance
-
Liquidity needs.
Research ranges are useful for understanding diversification, but personal asset allocation should be based on the investor's complete financial situation.
100% Equity vs Equity Plus Gold
Consider two simplified portfolios.
Portfolio A
- 100% equity
Portfolio B
- equity plus a modest gold allocation
During a powerful equity bull market, Portfolio A may generate higher returns because more money remains invested in growth assets. During a severe equity drawdown, however, Portfolio B may fall less if gold holds up better than stocks.
That lower drawdown can have another practical benefit: investors may find it psychologically easier to remain invested rather than panic-selling at depressed prices. Diversification therefore has both a mathematical and behavioural role.
When Gold May Not Protect Your Portfolio
Investors should also understand the conditions under which gold may disappoint.
1. Short-term liquidity panics
During extreme market stress, investors sometimes sell assets across the board to raise cash. Gold can temporarily decline alongside equities.
2. Rising real interest rates
Gold does not pay interest. When inflation-adjusted yields on competing assets become more attractive, gold may face pressure.
3. Buying after a sharp rally
A safe-haven asset can still become expensive. Buying only because prices have already surged can expose an investor to a correction.
4. Long periods of equity strength
During strong economic expansion and rising corporate profits, equities may significantly outperform gold.
5. Costs associated with physical gold
Jewellery may involve making charges and other costs. Physical gold also creates questions around storage, purity, and resale. These limitations are why gold should generally be evaluated as part of the entire portfolio rather than in isolation.
Physical Gold vs Gold ETF vs Gold Fund
Indian investors have several ways to gain exposure to gold.
|
Factor |
Physical Gold |
Gold ETF |
Gold Mutual Fund |
|
Form |
Physical metal/jewellery |
Exchange-traded investment |
Mutual fund investment |
|
Storage required |
Yes |
No |
No |
|
Purity concern |
Possible |
No physical purity issue for investor |
No physical purity issue for investor |
|
Liquidity |
Depends on seller/buyer |
Traded on exchange |
Redeemed through fund platform |
|
Costs |
Making/storage/resale costs may apply |
Brokerage + fund expenses may apply |
Fund expenses may apply |
|
Best suited for |
Physical ownership/use |
Investment exposure to gold |
Investors preferring mutual-fund route |
The right option depends on the purpose of the purchase. Gold bought for jewellery consumption is different from gold held purely as a portfolio investment.
Investors should also check the latest taxation, product rules, expense ratios and regulatory information before investing because these can change over time.
Should You Sell Stocks and Buy Gold During a Correction?
For a long-term investor, making an all-or-nothing switch solely because markets have already fallen can create a new risk: missing the subsequent equity recovery. Nobody knows the exact market bottom in advance.
Instead of reacting to headlines, investors can focus on whether their original asset allocation still matches their financial goals and risk tolerance.
For example, if an investor has already established a long-term allocation across equity, gold, debt and cash, a market correction may be a reason to review and rebalance that allocation rather than abandon one asset class entirely.
Rebalancing means bringing the portfolio back towards its chosen asset mix after market movements have changed the percentages.
Should Equity SIPs Continue During a Market Correction?
For investors using systematic investment plans for long-term goals, a market decline means the same contribution can purchase more mutual-fund units when NAVs are lower.
However, continuing any investment strategy should depend on:
-
Financial goals
-
Emergency savings
-
Income stability
-
Time horizon
-
Risk tolerance.
Money that may be required in the near future should not automatically be exposed to equity-market risk simply because markets have fallen.
Gold or Cash During a Market Correction?
Gold and cash serve different purposes. Cash or liquid emergency reserves are designed to cover near-term expenses and unexpected financial needs.
Gold is an investment asset whose value fluctuates. Gold should therefore not automatically replace an emergency fund.
An investor may hold both:
-
Sufficient liquid reserves for emergencies, and
-
Gold as part of a diversified investment portfolio.
Gold vs Equity: Which Is Better During a Market Correction?
There is no permanent winner. During periods of severe equity stress, gold has often demonstrated useful diversification characteristics. During periods of strong economic and corporate growth, equities can benefit from rising earnings and business expansion.
Their portfolio roles are therefore different:
-
Gold can support diversification and portfolio resilience.
-
Equity provides exposure to long-term business and economic growth.
Trying to predict which asset will outperform next can be much harder than maintaining a diversified asset-allocation strategy that is appropriate for the investor's goals.
Conclusion
The gold vs equity during a market correction debate should not be reduced to choosing one asset and abandoning the other.
History shows that gold has often helped diversify portfolios during periods of severe market stress. But gold is not guaranteed to rise whenever stocks fall, and it can experience extended periods of weak performance.
Equities serve a different purpose. They give investors ownership in businesses and exposure to long-term economic and earnings growth, but they can experience significant short-term drawdowns.
(Sources: Livecmint, Upstox, ET , Businesstoday, Nasdaq

DISCLAIMER: This blog is NOT any buy or sell recommendation. No investment or trading advice is given. The content is only for educational purposes. Always discuss with your SEBI-registered financial advisor for investment-related decisions.
Follow this WhatsApp Channel for the latest updates directly on WhatsApp.
.webp)
.webp)