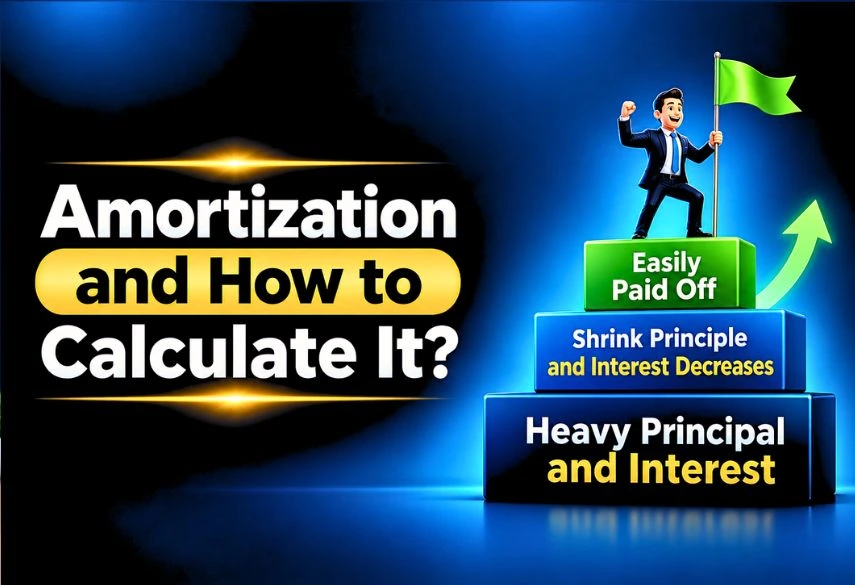
Amortization is the process of paying off a loan through regular fixed payments that cover both interest and principal until the debt is fully cleared. An amortization schedule shows exactly how each payment splits between interest and principal and tracks the remaining balance over time.
This beginner-friendly guide explains what amortization is, how amortization works, the amortization formula, and how to calculate amortization with clear examples, tables, and practical tips.
What Is Amortization?
In simple terms, amortization means spreading a large loan into smaller, equal monthly payments over a fixed period. Most home loans, car loans, and personal loans follow this method. Every payment has two parts: interest (the cost of borrowing) and principal (the amount you originally borrowed). Early payments are mostly interest. As the balance drops, more of each payment goes toward principal.
This system benefits both the lender and the borrower. The lender earns interest steadily, while you know your exact monthly payment and the exact date the loan will end. Understanding amortization helps you plan your budget, compare loan offers, and decide whether making extra payments is worth it.
How Does Amortization Work?
How does amortization work in real life? Interest is always calculated first on the current outstanding balance. Whatever remains of your fixed payment reduces the principal. Because the balance gets smaller each month, the interest portion also shrinks. This gradual shift is the core of amortization.
On a long mortgage, the first several years can feel slow because most of your payment covers interest. Later in the loan, almost every dollar reduces the principal. Shorter terms (such as 15 years instead of 30) cost less total interest even though the monthly payment is higher. This is why reviewing an amortization schedule is so useful before you sign any loan papers.
What Is an Amortization Schedule?
An amortization schedule (also called an amortization table) is a complete list of every payment you will make. It typically includes:
-
Payment number or date
-
Total payment amount
-
Interest portion
-
Principal portion
-
Remaining loan balance
-
Sometimes cumulative interest paid so far.
A clear loan amortization schedule or mortgage amortization schedule acts like a roadmap. You can see when your balance will drop below certain levels and how much total interest you will pay over the full term. Lenders usually provide one, but you can also create your own with an amortization calculator or a free amortization calculator.
The Amortization Formula Explained Simply
To learn how to calculate amortization, start with the standard monthly payment formula used for fixed-rate loans:

Where:
- M = Monthly payment
- P = Principal (loan amount)
- r = Monthly interest rate (annual rate ÷ 12)
- n = Total number of monthly payments (years × 12)
Once you have the fixed monthly payment, each row of the schedule is calculated as follows:
1. Interest for the month = Remaining balance × monthly rate
2. Principal for the month = Monthly payment − Interest
3. New balance = Previous balance − Principal paid
This process continues until the balance reaches zero. The final payment is often adjusted slightly to clear any remaining cents.
Step-by-Step Example with an Amortization Table
Let’s build a simple example so you can see the process clearly.
Loan details:
- Principal: $200,000
- Annual interest rate: 6%
- Term: 15 years
Monthly rate r = 0.06 ÷ 12 = 0.005
Number of payments n = 15 × 12 = 180
Monthly payment M ≈ $1,687.71
Here is a sample of the first five months of the amortization table:
|
Month |
Payment |
Interest |
Principal |
Remaining Balance |
|
1 |
$1,687.71 |
$1,000.00 |
$687.71 |
$199,312.29 |
|
2 |
$1,687.71 |
$996.56 |
$691.15 |
$198,621.14 |
|
3 |
$1,687.71 |
$993.11 |
$694.60 |
$197,926.54 |
|
4 |
$1,687.71 |
$989.63 |
$698.08 |
$197,228.46 |
|
5 |
$1,687.71 |
$986.14 |
$701.57 |
$196,526.89 |
Notice how the interest drops a little each month while the principal portion grows. By the end of 15 years, the balance reaches exactly zero. You can create a full loan amortization schedule or mortgage amortization schedule using any free amortization calculator or a spreadsheet.
Mortgage Amortization vs Auto Loan Amortization Schedule
Mortgage amortization usually involves larger amounts and longer terms (15 or 30 years). Because of the long timeline, early payments are heavily weighted toward interest. An auto loan amortization schedule is typically shorter (3–7 years), so the shift from interest to principal happens faster.
Both use the same amortization formula and the same calculation method. The main differences are loan size, term length, and interest rate. Looking at either schedule helps you decide whether to refinance, make extra payments, or choose a shorter term.
Amortization Schedule with Extra Payments
One of the most powerful features of an amortization schedule is the ability to test extra payments. Adding even a small amount to the principal each month reduces the balance faster. This lowers future interest charges and shortens the loan term.
For example, adding $100 extra every month to the $200,000 loan above can cut several years off the term and save thousands in interest. Many amortization schedule calculators and mortgage amortization calculators let you model different extra payment amounts and instantly show the new payoff date and total interest saved. This makes a free amortization calculator especially useful for long-term planning.
Why Understanding Amortization Matters
Knowing what amortization is and how an amortization schedule works gives you real control over your debt. You can:
-
Compare different loan offers accurately
-
See the true long-term cost of a loan
-
Decide if refinancing makes financial sense
-
Plan extra payments strategically
-
Budget better because you know exactly what each payment does.
Many people feel frustrated when early payments seem to go mostly toward interest. Looking at the full schedule shows that the balance does drop steadily and that later payments become much more effective at building equity.
Easy Ways to Create Your Own Schedule
You do not need to calculate everything by hand. A good amortization calculator or loan amortization calculator does the math instantly. You enter the loan amount, interest rate, and term, and it produces a complete amortization table.
Some tools also allow extra payments, different payment frequencies, or downloading the schedule as a spreadsheet. Reliable free tools are available on major financial websites.
If you prefer spreadsheets, Excel or Google Sheets can generate a full schedule using the PMT, IPMT, and PPMT functions. Once you understand the basic amortization formula, building or reading any schedule becomes straightforward.
Conclusion
Amortization is simply the organized way loans are repaid over time. An amortization schedule turns that process into a clear, month-by-month picture. By learning how to calculate amortization and reading your own schedule, you gain real power over your debt.
Whether you are looking at a mortgage amortization schedule, an auto loan amortization schedule, or testing an amortization schedule with extra payments, this knowledge helps you make smarter money decisions and reach financial freedom faster.
(Sources: Amortization.us, Wellsfargo,Fidelity)

DISCLAIMER: This blog is NOT any buy or sell recommendation. No investment or trading advice is given. The content is only for educational purposes. Always discuss with your SEBI-registered financial advisor for investment-related decisions.
Follow this WhatsApp Channel for the latest updates directly on WhatsApp.
.jpeg "Mortgage Loans")