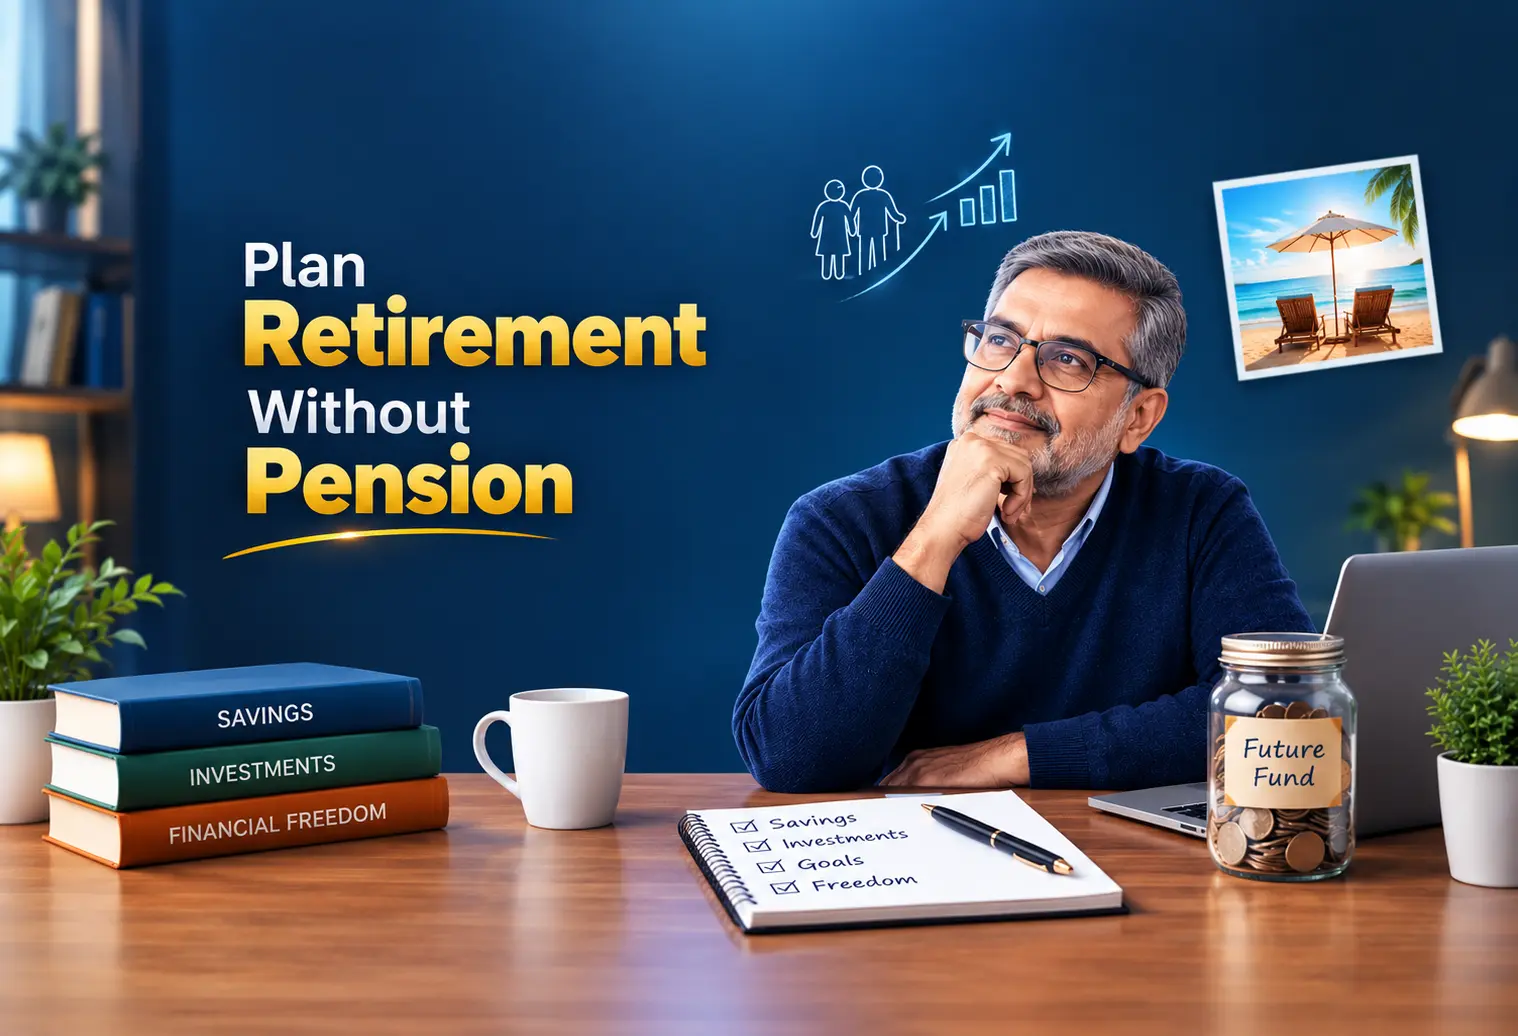
You can still build a secure, comfortable retirement even without a pension. The practical solution is to start saving consistently through NPS, PPF, EPF (if available), mutual fund SIPs, and other options; aim to set aside 20–30% of your income and create your own reliable monthly income using systematic withdrawals, annuities, and other sources. This approach turns your personal savings into a self-funded pension that works for you throughout retirement.
Most Indians face this exact situation today. Around 80% of people retire without any formal pension or structured monthly income. Traditional employer pensions are rare outside government jobs and a handful of large private companies.
Private-sector employees, self-employed professionals, freelancers, gig workers, small business owners, and homemakers usually have to create their own retirement plans. The encouraging part is that India now offers excellent, accessible tools for financial planning for retirement, and these tools are available to almost everyone, whether you earn a salary or run your own work.
Why Most Indians Have No Pension
In earlier decades, only government employees and a few private companies offered defined-benefit pensions that paid a fixed amount every month for life. Today, the picture has changed completely.
Most of the workforce depends entirely on personal savings. EPF gives some salaried people a useful starting point, but the amount that accumulates is often not enough for a comfortable lifestyle after retirement.
Self-employed people and those working in the informal or gig economy usually begin with zero. This reality makes pension retirement planning essential for the vast majority of Indians.
Without a pension, you need a clear plan to replace your monthly salary or business income once you stop working. Inflation in India (especially healthcare inflation) can quietly erode the value of money over 20–30 years. That is why starting early and staying consistent matters so much.
Step 1: Calculate How Much Money You Will Actually Need
The first practical step in planning for retirement is estimating your future expenses. A widely used guideline is that you will need 70–80% of your current monthly expenses to maintain a similar lifestyle after retirement. However, healthcare costs in India often rise faster than general inflation, so it is wise to plan a little extra for medical needs, medicines, and possible long-term care.
A simple and popular rule among Indian planners is to target a corpus of 25 to 33 times your expected annual expenses at the time of retirement. For example, if you expect to need ₹1.2 lakh per month (₹14.4 lakh per year) in today’s terms after adjusting for inflation, you may need a corpus of roughly ₹3.5–4.5 crore or more depending on how long you expect to live and the safe withdrawal rate you choose.
Free retirement planning calculators available on many Indian financial websites and apps can help you run personalised numbers. You simply enter your current age, expected retirement age, present monthly expenses, and assumed inflation rate (usually 6–7%). The calculator then shows the target corpus and the monthly investment required.
Most financial experts in India recommend saving 20–30% of post-tax income for a comfortable retirement at the normal age of 58–60. Those who start in their 20s can begin with a lower percentage and increase it over time. Those who start in their 40s or later usually need to aim for the higher end of the range or even more.
Step 2: Choose the Right Investment Options Available in India
You do not need an employer pension to begin building wealth. India offers several strong and tax-efficient options that almost anyone can use:
-
NPS (National Pension System): Open to all Indian citizens between 18 and 70 years. It is low-cost, offers market-linked returns, and gives an extra tax deduction of ₹50,000 under Section 80CCD(1B) under the old tax regime.
-
PPF (Public Provident Fund): Completely tax-free under the EEE model (Exempt-Exempt-Exempt). The current interest rate is around 7.1%. Maximum investment is ₹1.5 lakh per financial year with a 15-year lock-in.
-
EPF and VPF: Available to salaried employees. The current interest rate is 8.25%. Voluntary Provident Fund (VPF) allows you to contribute extra beyond the mandatory 12%.
-
Equity Mutual Fund SIPs: Excellent for long-term wealth creation. Systematic Investment Plans help you invest regularly and average out market ups and downs.
-
Debt funds, hybrid funds and senior citizen schemes: Useful for balancing risk as you get closer to retirement.
-
Annuities: Can provide guaranteed monthly income after retirement.
These options together form the foundation of how to save for retirement without a pension.
Comparison of Key Retirement Options in India (2026)
|
Option |
Who Can Open It |
Annual Limit / Contribution |
Approximate Returns |
Tax Benefit |
Best Suited For |
|
NPS Tier-I |
Any Indian citizen (18–70) |
No upper limit (min ₹1,000/year) |
9–12% (market-linked) |
80C + extra ₹50,000 (80CCD 1B) |
Growth + extra tax saving |
|
PPF |
Any resident Indian |
Maximum ₹1.5 lakh |
7.1% (guaranteed) |
Fully tax-free (EEE) |
Safety and tax-free corpus |
|
EPF / VPF |
Salaried employees |
12% of basic (VPF can be higher) |
8.25% (guaranteed) |
Tax benefits within limits |
Salaried people with employer contribution |
|
Equity Mutual Fund SIPs |
Anyone |
No limit |
10–12% historical |
LTCG tax above ₹1.25 lakh |
Long-term high growth |
|
Senior Citizen / Annuity schemes |
After age 60 |
Varies |
Fixed or market-linked |
Taxable as per slab |
Regular monthly income |
(Data based on current EPFO, PFRDA and government-notified rates for 2026).
Step 3: Make Saving Automatic and Increase It Gradually
The biggest challenge for most people is consistency. The easiest way to overcome this is automation. Start SIPs in mutual funds or contributions to NPS on the same day your salary or business income arrives. Treat retirement savings like any other fixed monthly bill.
If you are salaried and already have EPF, continue the mandatory contribution and consider adding Voluntary Provident Fund (VPF) for extra safe savings. For self-employed people and freelancers, NPS and PPF become the main pillars, supported by equity SIPs.
A powerful technique is the step-up SIP. Start with an amount you can comfortably afford and increase it by 10% every year as your income grows. This method feels less painful and produces much larger results over 15–25 years because of compounding.
Step 4: Turn Your Corpus into Reliable Monthly Income
Building a large nest egg is only half the job. The other half is converting that money into steady income that lasts as long as you live. A practical multi-layer approach that works well in India includes:
1. NPS Annuity– At the time of exit, a portion of your NPS corpus can be used to buy a lifetime annuity that pays you every month.
2. Systematic Withdrawal Plan (SWP) from mutual funds – Gives you flexible monthly income while the remaining money stays invested.
3. Senior Citizen Savings Scheme (SCSS), Post Office Monthly Income Scheme, or bank fixed deposits– Provide safety and predictable interest.
4. Rental income or part-time consulting– Useful additional support if available.
In the Indian context, many planners suggest a safe withdrawal rate of around 3–4% per year, taking into account higher inflation and longer life expectancy compared to some other countries.
Real-Life Style Examples
Example 1 – Salaried professional
Rahul is 32, earns ₹12 lakh per year and currently has only EPF. He starts a ₹15,000 monthly SIP in equity funds, contributes the maximum possible to PPF, and puts an extra ₹5,000 into NPS for the additional tax benefit. He increases the SIP by 10% every year. By age 60 he can reasonably expect a substantial corpus that, combined with EPF, can support a comfortable lifestyle.
Example 2 – Self-employed / freelancer
Meera is 40 and runs her own design studio. She has no EPF. She opens an NPS account, maxes her PPF every year, and starts a ₹25,000 monthly SIP. She also builds an emergency fund equal to 12 months of expenses. Even starting later, the combination of disciplined saving and step-up investments can still create a solid retirement fund.
Common Mistakes That Can Hurt Your Plan
- Starting too late and underestimating the combined effect of inflation and healthcare costs.
- Withdrawing EPF or breaking PPF early for non-essential goals.
- Keeping almost all money only in fixed deposits or low-return options for decades.
- Ignoring the extra ₹50,000 tax benefit available under NPS in the old tax regime.
- Not reviewing the plan every year or after major life changes such as a job switch or business expansion.
- Forgetting to buy adequate health insurance before retirement.
Taking financial advice for retirement planningfrom a SEBI-registered investment advisor can be helpful if your situation is complex or if you have multiple goals running together. Many good retirement planning servicesand online tools are now available in India at reasonable cost.
A Simple Action Plan You Can Start This Month
1. Open an NPS account online (it takes only a few minutes with Aadhaar and PAN) and a PPF account if you do not already have one.
2. Start or increase a dedicated retirement SIP in equity or hybrid mutual funds.
3. Use a free retirement calculator to set a realistic target corpus and monthly investment amount.
4. Automate all contributions so the money moves without depending on willpower.
5. Increase the investment amount by at least 10% every year.
6. Review the complete plan once a year and adjust for changes in income, expenses or goals.
Conclusion
How to plan retirement without a pensionis no longer a mystery. Whether you are 25, 35 or 50, the same core principles apply: save regularly, use tax-efficient options such as NPS and PPF, invest a meaningful portion for growth through SIPs, protect yourself with health insurance, and plan how you will generate income after you stop working. Consistency matters far more than perfection.
Your future self will thank you for the decisions you make today. The earlier you begin, the lighter the monthly effort required. Even if you are starting later than you would have liked, a focused and disciplined plan can still create meaningful security.
(Sources : Policybazaar ,ET , Livemint ,Etmoney)

DISCLAIMER: This blog is NOT any buy or sell recommendation. No investment or trading advice is given. The content is only for educational purposes. Always discuss with your SEBI-registered financial advisor for investment-related decisions.
Follow this WhatsApp Channel for the latest updates directly on WhatsApp.
.jpeg)
.jpeg)