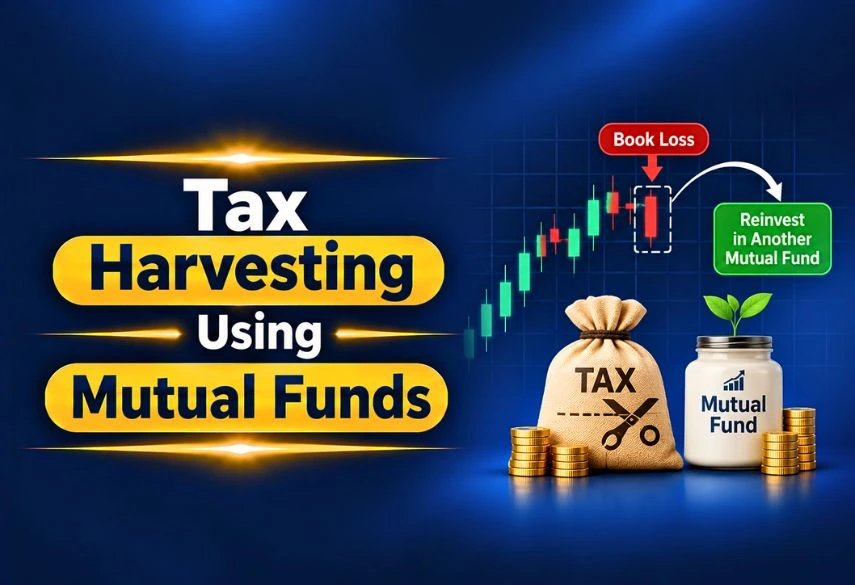
Tax harvesting using mutual funds is a simple, legal way to lower your capital gains tax. You sell units that are currently in loss (or book limited gains) and use that to reduce or wipe out tax on your profitable investments in the same year. This strategy works especially well with equity mutual funds in India and can save you thousands every financial year if done correctly.
In this beginner-friendly guide, you will learn exactly how to do tax harvesting in mutual funds, the difference between tax-loss and tax-gain harvesting, current tax rules, step-by-step process, real examples, and important rules like set-off and carry-forward. Everything is explained in simple words so even a first-time investor can follow it.
What is Tax Harvesting in Mutual Funds?
Tax harvesting is a smart tax-planning method where you deliberately sell mutual fund units to create a tax benefit. There are two main types:
-
Tax-loss harvesting: You sell units that have fallen below your purchase price. The loss you book can reduce the tax you pay on other gains.
-
Tax-gain harvesting: You sell units that have made long-term profit (but within the tax-free limit) and reinvest the money. This uses up your free limit and resets your cost higher for the future.
Both are completely legal under Indian tax laws. Investors use tax loss harvesting mutual funds and tax harvesting mutual funds strategies every year, especially before 31 March, to lower their overall tax bill.
Current Tax Rules on Equity Mutual Funds (2026)
Understanding mutual fund capital gains tax and tax on equity mutual funds is the foundation of any harvesting plan.
|
Type of Gain |
Holding Period |
Tax Rate |
Exemption |
|
Short-Term Capital Gain (STCG) |
12 months or less |
20% + cess |
No exemption |
|
Long-Term Capital Gain (LTCG) |
More than 12 months |
12.5% + cess |
First ₹1.25 lakh free every year |
These rates apply to equity-oriented mutual funds (those investing at least 65% in equity). For debt or specified mutual funds bought after 1 April 2023, gains are taxed at your income-tax slab rate no matter how long you hold them.
The LTCG exemption limit of ₹1.25 lakh is one of the most useful tools for tax-gain harvesting.
How Set-Off Works: Mutual Fund Loss Set Off Rules
This is the heart of tax loss harvesting India.
-
A short-term capital loss (STCL) can be set off against both STCG and LTCG.
-
A long-term capital loss (LTCL) can be set off only against LTCG.
-
If you cannot use the full loss in the same year, you can carry forward capital loss for up to 8 assessment years. You must file your ITR on time to keep this benefit.
This is why capital loss set off mutual funds and mutual fund loss set off are powerful tools. A loss booked this year can save tax even in future years.
Step-by-Step: How to Do Tax Harvesting in Mutual Funds
Here is the practical process anyone can follow:
1. Check your portfolio
Log into MF Central, CAMS, or your broker app. Note which funds are in profit and which are in loss. Also check your realised gains for the current financial year.
2. Identify the type of loss or gain
Look at the purchase date of each lot. For SIPs, the FIFO method mutual funds (First-In-First-Out) applies - the oldest units are considered sold first. This is important for correct SIP capital gains calculation.
3. Decide between loss or gain harvesting
-
If you have taxable gains and some funds in loss → do tax-loss harvesting.
-
If you have unrealised long-term gains near or below ₹1.25 lakh → do tax-gain harvesting.
4. Redeem or switch the units
Sell the loss-making (or limited-gain) units. You can also switch to another scheme of the same AMC. A switch is treated as a sale for tax purposes.
5. Reinvest immediately
Put the money back into the same fund or a similar fund the same day or next day. India has no wash-sale rule, so this is allowed. Staying invested is important so you do not miss market recovery.
6. Keep records and file correctly
Download capital gains statements and report everything accurately in your ITR. Do this exercise ideally by mid-March so the transaction settles before 31 March.
Real-Life Example with Numbers
Suppose this is your situation in a financial year:
|
Investment |
Purchase Value |
Current/Sale Value |
Gain / Loss |
Holding Period |
|
Equity Fund A |
₹5,00,000 |
₹7,00,000 |
-+₹2,00,000 LTCG |
18 months |
|
Equity Fund B |
₹3,00,000 |
₹2,40,000 |
-₹60,000 LTCL |
15 months |
Without harvesting:
Taxable LTCG = ₹2,00,000 – ₹1,25,000 = ₹75,000
Tax at 12.5% = ₹9,375
With tax-loss harvesting:
You sell Fund B and book ₹60,000 loss.
Net LTCG = ₹2,00,000 – ₹60,000 = ₹1,40,000
Taxable amount = ₹1,40,000 – ₹1,25,000 = ₹15,000
Tax at 12.5% = ₹1,875
You save ₹7,500 just by booking the loss and staying invested.
When Tax Loss Harvesting Equity Mutual Funds Makes Sense
-
You already have taxable capital gains this year.
-
The loss is meaningful (usually ₹50,000 or more).
-
The fund is past its exit-load period, or the tax saving is bigger than the exit load.
-
You are ready to reinvest so your money continues to grow.
It is less useful if your losses are very small or if you have no gains to offset.
Special Note on ELSS and Other Funds
ELSS tax benefits come under Section 80C (up to ₹1.5 lakh deduction). However, ELSS funds have a 3-year lock-in, so you cannot redeem them for tax harvesting until the lock-in ends. Once free, the normal LTCG rules apply.
For pure debt funds bought after April 2023, losses are treated as short-term and can be set off against any capital gains, which sometimes makes them useful tools too.
Common Mistakes to Avoid
-
Waiting till the last day of March (settlement may spill into next year).
-
Forgetting exit loads.
-
Not reinvesting and staying out of the market.
-
Mixing up STCL and LTCL set-off rules.
-
Not filing ITR on time and losing the carry-forward benefit.
Conclusion
Tax harvesting is one of the smartest ways to save tax on capital gains without changing your long-term investment plan. Whether you use tax loss harvesting equity mutual funds or the simpler tax-gain method, the key is understanding the rules of mutual fund taxation, using the LTCG exemption limit, and following the set-off and carry-forward provisions correctly.
Start by reviewing your portfolio this month. Identify any loss-making units, calculate the possible tax saving, and act before the financial year ends. With a little planning, tax harvesting mutual funds can put extra money back in your pocket year after year while your investments continue to grow.
(Sources:Value Research Online , INDMoney ,Bajaj AMC ,ET Money)

DISCLAIMER: This blog is NOT any buy or sell recommendation. No investment or trading advice is given. The content is only for educational purposes. Always discuss with your SEBI-registered financial advisor for investment-related decisions.
Follow this WhatsApp Channel for the latest updates directly on WhatsApp.